9 September, 2021
Press Coverage of the HWBC Office Review & Outlook H1 2021
Catch up on the various press coverage of our Office Review & Outlook H1 2021

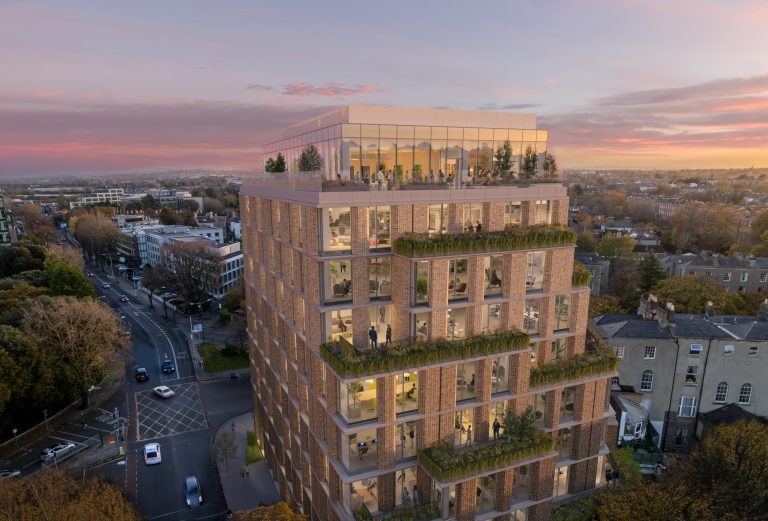
Office market set for V-shaped recovery in 2022.
With the office market in effective lockdown for the last 15 months, there are now increasing signs of pent up demand from occupiers, with much stronger take up levels recorded in Q2. The staggered lifting of Covid restrictions and the successful vaccine roll-out has led to a bounce in economic activity, with recent figures for the services sector and tax revenues showing strong recovery.
We have seen a marked increase in tenant activity heading into Q3 which will translate to increased take up for the full year. All the signs are for a strong recovery in 2022 and a return to more normalised levels of activity, albeit from the low levels of the pandemic.
Key market statistics
Office supply pipeline
Suburban market
Outlook
There are now signs that the impact of the pandemic on the Dublin office market is starting to ease, as occupiers look ahead to decide the right blend of office space and remote working to suit their business and staff profile. Most companies are targeting September or October to have protocols in place for staff returning to the office, and this will lead to increased deal activity over the coming quarters.
We estimate the current market correction will continue into 2022 and then stabilise, with growth returning from 2023 onwards. We are seeing evidence of pent up demand from occupiers with a positive start to Q3, which is traditionally a quiet time due to holiday season, and this bodes well for a strong finish to the year. Assuming no serious variants emerge with Covid, all the signs are that 2022 will see a return to more normalised levels of demand activity, with transactions back to the long-term average for the market.
Headline office rents (H1 2021)
| CBD (Grade A) | €55.00 – €57.50 per sq ft (NIA) |
| Suburban (Grade A) | €30.00 – €32.50 per sq ft plus (GIA) |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,750 – €2,000 pa per car space |
Office statistics, H1 2021
| Take up, H1 2021 | 209,000 sq ft |
| New completions, H1 2021 | 472,350 sq ft |
| Vacancy rate, entire market | 10.15% |
| Vacancy rate, Dublin 2 | 8.10% |
| Vacancy rate, Dublin 4 | 14.60% |
| Pre-committed on practical completion | 52.0% |
| Under construction, CBD | 4.97m sq ft |
| Under construction, suburbs | 195,000 sq ft |
CBD pipeline
| Year | Estimated full year completions (sq ft) | Pre-let / reserved (sq ft) | New space available (sq ft) |
|---|---|---|---|
| 2021 | 2.02m | 1.275m / 63% | 745,000 |
| 2022 | 2.05m | 1.07m / 52% | 980,000 |
| 2023 | 1.37m | 450,000 / 33% | 920,000 |
Top 5 office deals, 2021
| Building | Size (sq ft) | Tenant |
|---|---|---|
| Connaught House, Burlington Road, D4 | 18,850 | Philip Lee |
| 24/26 City Quay, South Docks, D2 | 14,725 | Euro Refreshments |
| One Kilmainham Square, D8 | 11,500 | HSE |
| Burlington Plaza, Burlington Road, D4 | 11,000 | Amazon |
| Nexus Building, Blanchardstown, D15 | 11,000 | GMC Utilities |
9 September, 2021
Catch up on the various press coverage of our Office Review & Outlook H1 2021
9 September, 2021
Strong recovery expected after a sharp decline in take up hits prime city rents
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.