11 February, 2022
Press Coverage of the HWBC Office Review & Outlook 2021 – 2022
Catch up on the various press coverage of our Office Review & Outlook 2021 – 2022

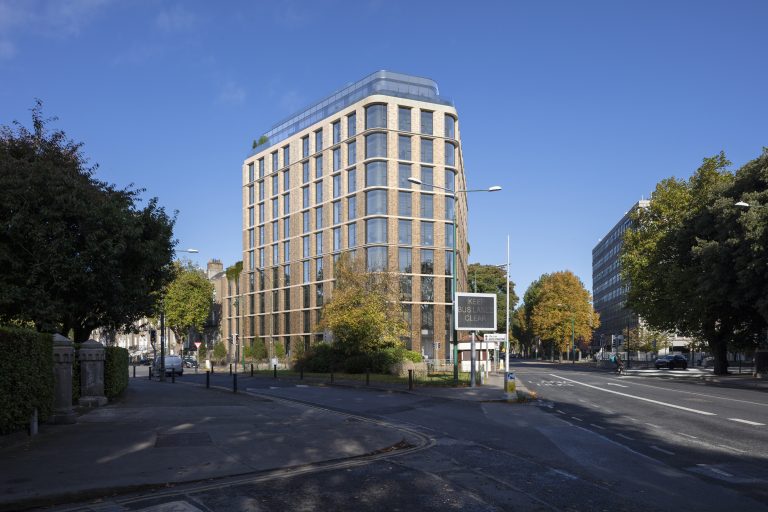
Strong Q4 sees Dublin market turning a corner.
2021 was a bumpy year for the Dublin office market, as uncertainty over the trajectory of the virus saw a poor first half in terms of tenant activity and low take up. It was noticeable, however, that companies were postponing requirements as opposed to cancelling. This led to a build of demand and a very strong finish to the year. The strong pipeline of transactions has carried over, with over 800,000 sq ft of deals reserved and expected to sign in 2022.
Key market statistics
Office supply and new construction
The push to go green
Sustainability and green credentials are now one of the most important factors for tenants choosing a new office location, and increasingly some companies will not consider older buildings with poor energy ratings. This trend is likely to accelerate as environmental, social and governance become key to corporate strategies and investment decisions.
Many stakeholders in the market, including funds and institutional landlords, have already recognised this development and are actively looking to replace older stock within portfolios to achieve ambitious net zero carbon targets by 2030. This is a positive development for the market, and replacing older stock will have the twin benefits of providing better quality space for occupiers and helping reduce the carbon footprint of the built environment.
Outlook
We expect 2022 to be a year of recovery for the office market in terms of take up, with levels moving back towards the long-term average. After a difficult two years the market should continue to stabilise in terms of prime headline rents and a tapering of tenant incentives available to occupiers. The lifting of restrictions and gradual return to the office should support the recovery, assuming no new variants of concern emerge.
The demand for new or quality upgraded buildings will increase, as occupiers show a clear preference for buildings with high sustainability credentials and staff amenities.
The technology sector and FDI continue to dominate the market in Dublin, and there was some concern that the new minimum tax agreement could have a negative effect on demand. This has not been the case and the IDA had a record year in terms of new overseas investment and job creation. In some ways the new tax agreement could be viewed as a positive, removing uncertainty now that the tax issue is off the table.
There is an emerging value premium in terms of rent and capital value between older buildings and modern stock, as tenants in many cases will not consider buildings with poor energy ratings. This ‘flight to quality’ will continue as older stock struggles to compete with Grade A in terms of the standard of staff amenities. The era of hybrid working has become a feature of the market over the last two years, and new Government legislation should be in place by year end to bring more clarity to both staff and employers on future work practices.
Headline office rents (Q4 2021)
| CBD (Grade A) | €55.00 – €57.50 per sq ft |
| Suburban (Grade A) | €30.00 – €32.50 per sq ft |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,750 – €2,000 pa per car space |
Office statistics, Q4 2021
| Take up, 2021 | 1.62m sq ft |
| New completions, FY 2021 | 1.25m sq ft |
| Long term average | 2.20m sq ft |
| Pre-committed on practical completion | 63% |
| Vacancy rate, entire market | 9.60% |
| Vacancy rate, Dublin 2 | 5.50% |
| Vacancy rate, Dublin 4 | 12.90% |
| Under construction, CBD | 4.32m sq ft |
| Under construction, suburbs | 0.10m sq ft |
Top 10 office deals, 2021
| Building | Size (sq ft) | Tenant |
|---|---|---|
| Harcourt Square, Harcourt Street, D2 | 288,500 | KPMG |
| Sorting Office | 216,000 | TikTok |
| One Park Place, Upper Hatch Street, D2 | 57,000 | |
| Termini, Sandyford, D18 | 44,000 | BNP Paribas |
| Three Gateway, East Wall, D3 | 43,000 | ESB |
| B10 Cherrywood, D18 | 36,500 | Accenture |
| 40 Molesworth Street, D2 | 30,000 | DLA Piper |
| 140 Pembroke Road, Ballsbridge, D4 | 27,500 | Bord Bia |
| 6-13 Pembroke Row, D2 | 27,500 | Data Protection Commissioner |
| Two Stemple Exchange, Blanchardstown, D15 | 27,000 | Veritas |
11 February, 2022
Catch up on the various press coverage of our Office Review & Outlook 2021 – 2022
11 February, 2022
Strong Q4 sees Dublin market turning a corner
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.