16 September, 2019
Press Coverage of the latest HWBC Office Report H1 2019
Read various press coverage of the latest HWBC Office Report H1 2019

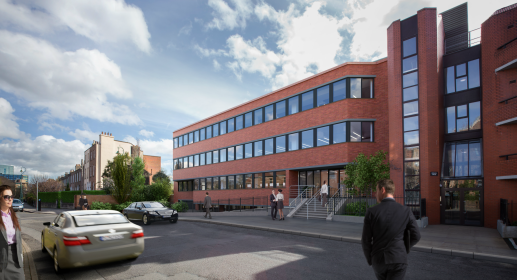
High level of pre-commitments continue in H1 2019.
The first six months of 2019 have been strong in terms of overall office take up, with 1.73m sq ft of recorded transactions and the bulk of activity occurring in Q1. The top five deals of the year so far were all signed in Q1 and, not surprisingly, dominated by US tech firms.
Salesforce and Facebook accounted for over 600,000 sq ft of take up between them, with Salesforce signing the largest ever single letting of 430,000 sq ft for their new campus in the north Docklands, and Facebook taking 175,000 sq ft at the newly refurbished Nova Atria South in Sandyford.
The Government sector has been active in the market, with the Central Bank taking 200,000 sq ft in Dublin Landings in the north docks and the OPW pre-letting 160,000 sq ft in Smithfield for the newly formed Tailte Eireann, following the merger of the Ordnance Survey Ireland and Valuation Office.
By contrast, the entire take up in Q2 was 380,000 sq ft, and the largest single transaction was Paddy Power taking 90,000 sq ft for expansion in Belfield Office Campus in D4. Although take up in Q2 was well below average, there are a number of significant transactions expected to sign in Q3 and Q4 this year, with up to 1.0m sq ft of space reserved and in advanced stages of negotiation. Companies such as Amazon, WeWork and Slack are all in expansion mode and expected to sign contracts for additional office space in H2 2019.
The demand pipeline is also holding up well despite the recent record levels of take up, with the technology sector in particular showing no signs of slowing down. In addition to tech demand, the Government sector has a number of large mandates to fill over the next 12-24 months.
Office supply and new construction
The development market is keeping pace with occupier demand, with 4.85m sq ft under construction in Dublin at the end of June, 4.0m sq ft of which is located in the CBD and mainly in the north and south Docklands. Nearly half of the space under construction in the city and scheduled for completion by the end of 2021 is already reserved, and this rises to 84% for the space due to reach completion by the end of this year.
There has been 905,000 sq ft of newly completed space in H1 2019, with 75% of this pre-committed on or before practical completion. This is a key metric to track underlying occupier demand trends, and the strong pre-commitment levels are driving the majority of new schemes under construction being developed on a speculative basis. New completions in FY 2018 were 1.82m sq ft with 80% of this space pre-let on completion, and we expect a similar level of new stock for FY 2019.
Co-working
The co-working sector is still expanding in Dublin and looking for new opportunities, mainly in the CBD hotspots for occupier demand. Although not a new service to the market, companies like WeWork and Iconic have rebranded the concept to suit the more flexible work practices of the gig economy and technology generation.
In a strong market they are offering maximum flexibility to the corporate sector for expansion and new entrants or start-ups on a rapid growth path. This is now disrupting the traditional landlord market, and particularly demand in the 5,000 to 10,000 sq ft range. In addition to offering turn key space for start-ups and flex space, the co-working sector is relieving pressure for larger tenants, offering them speedy solutions for continued expansion with flexible exit options.
Suburbs
There is strong tenant demand for both city and suburban space, with a number of large requirements seeking over 100,000 sq ft currently active in the market. Headline rents in the prime suburban areas of Sandyford and Leopardstown are still rising and are now ranging €30.00 to €32.00 psf, with up to €35.00 psf achieved in Central Park. With tighter supply at the top end of the market, lease commitments are moving to minimum 10 years term certain for the larger transactions.
Big tech is still driving a lot of this demand, but there are also sectors such as fintech, medtech, pharma and life sciences adding to demand levels. Facebook have continued to expand their footprint in the suburbs, and Google are taking more space in Sandyford to add to their current facilities at The Chase and Blackthorn House.
There are now only two significant office buildings available in Sandyford, with The HIVE refurbishment due for completion in September providing 73,000 sq ft over four floors, and One South County completed during the summer with 135,000 sq ft over five levels. New space is under construction at Termini, Arkle Road, and will provide 220,000 sq ft by the end of 2020.
Brexit
The Brexit saga is still unresolved over three years from the vote to leave, and it now resembles something of a slow-motion crash with the latest twists and turns in London and the Conservative Party strategy. No one can predict what is going to happen next, but the EU may have taken a view to pull the plaster off as quickly as possible to minimise the pain of further delay and discussions.
Dublin has been the big winner in terms of announced Brexit relocations ahead of other locations such as Amsterdam, Paris and Frankfurt, however the majority of space requirements have been relatively modest thus far. This could change if there is to be a no deal exit, and the much anticipated wave of new demand for Dublin offices might actually transpire, putting some upward pressure on current CBD rental levels.
Rents
Rental levels for prime CBD space have remained stable over the last six months, with typical headline rents ranging from €60.00 to €65.00 psf being agreed for the best quality space. Assuming an orderly Brexit, we do not expect upward pressure on prime rents over the immediate term, as more speculative space comes on stream to meet demand from both domestic and FDI occupiers.
Headline office rents (H1 2019)
| CBD (Grade A) | €60.00 – €65.00 per sq ft |
| Suburban (Grade A) | €30.00 – €32.00 per sq ft |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,750 pa per car space |
Office statistics, H1 2019
| Take up | 1.73m sq ft |
| Vacancy rate, entire market | 7.3% |
| Vacancy rate, CBD | 5.4% |
| Pre-committed, H1 2019 | 47% |
| New completions, H1 2019 | 905,000 sq ft |
| Pre-committed on practical completion | 75.0% |
| Estimated completions, FY 2019 | 1.75m sq ft |
| Under construction, CBD | 4.0m sq ft |
| Under construction, suburbs | 875,000 sq ft |
Top 5 office deals, H1 2019
| Building | Size (sq ft) | Tenant |
|---|---|---|
| Salesforce Tower, Spencer Place, D1 | 430,000 | Salesforce |
| Dublin Landings, D1 | 204,000 | Central Bank |
| Nova Atria South, Sandyford, D18 | 171,500 | |
| Distillers Building, Smithfield, D7 | 162,500 | OPW |
| 5 Hanover, South Docks, D2 | 98,600 | DocuSign |
16 September, 2019
Read various press coverage of the latest HWBC Office Report H1 2019
16 September, 2019
The first 6 months of 2019 have been strong in terms of overall office take up with 1.73m sq ft of recorded transactions, with the bulk of activity occurring in Q1. The top 5 deals of the year so far were all signed in Q1 and not surprisingly dominated by US tech firms.
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.