29 January, 2018
HWBC Releases Office Market Review & Outlook for 2018
2017 was a record year for the Dublin market with all the signs staying positive for the year ahead.

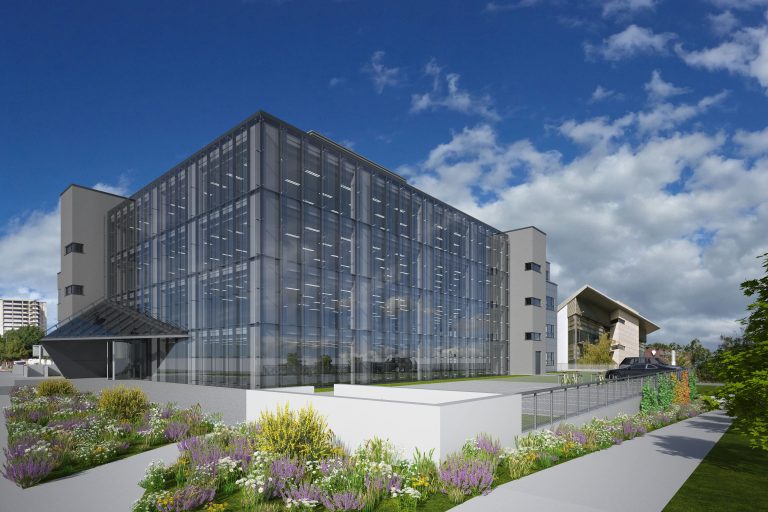
Record breaking 12 months for the Dublin office market.
Momentum has been building in the Dublin office market over the last few years, with pent up demand from occupiers resulting in the highest ever level of transactions recorded in 2017. Total take up for the year was 3.57m sq ft, with a number of new developments under construction securing large pre-commitments from high profile names such as JP Morgan, Indeed.com and AIB.
Although demand for space remains strong, it is unlikely this volume of take up will be reached again in 2018, mainly due to supply issues with fewer large schemes for completion over the next 12 months. Significant buildings likely to pre-let in 2018 include Three Park Place on Hatch Street, and Bolands Quay and 1 SJRQ in the south Docks, with most of the other planned developments pushed out to 2019 and beyond.
Although this cycle appears to be entering the mature recovery phase, there are no signs of the market running out of steam anytime soon, with demand well ahead of current supply levels, particularly within the CBD. Construction of new space is being scaled up in the city but is not yet having an effect on supply levels, as over 80% of new stock completed last year was reserved on or before completion.
Foreign direct investment
The Dublin market is heavily dependent on foreign direct investment, with the IDA continuing to outperform in attracting overseas business to Ireland despite stiff competition from the UK and Europe. FDI companies now employ over 200,000 people directly in Ireland, with Dublin the main beneficiary as the only location of international scale.
Dublin is particularly successful in attracting fintech and technology companies, with new entrants this year including KBRA, Jet.com, ViaSat and Tecknicor. There was also considerable expansion from existing and growing companies driving take up to record levels, with Facebook, Indeed.com, LinkedIn and Microsoft all taking space over 100,000 sq ft.
Reliance on the success of FDI has the potential for some downside risks. Exposure to international events such as Brexit, political uncertainty in Germany and tax changes in the US have some potential to disrupt the Dublin office market.
Rents
Prime office rents are still seeing upward pressure, reaching €65.00 psf in 2017 for the best space, however the majority of CBD transactions are in the €55.00 – €62.50 psf range. We expect prime rents to remain at these levels in 2018, with some exceptions likely for smaller suites or more flexible lease agreements.
It remains a landlord’s market, with further hardening of lease terms expected in 2018 including reduced rent free concessions, and break options pushed out with penalties, rather than prime headline rents continuing to rise at a similar pace to recent years.
Suburbs
The improved availability of space in the suburbs is becoming an attractive option for large corporate occupiers, and we see more scope for rent rises this year in the preferred locations such as Sandyford and Leopardstown. Dublin 18 has continued to attract the most interest from tenants, which was reinforced by Google’s decision to establish a significant suburban hub there in 2018.
In two of the largest office deals of the year, AIB pre-let the entire of Block H in Central Park (152,000 sq ft) from Green REIT, and Fleetmatics are taking 90,000 sq ft in the Atrium Buildings, which were previously occupied by Microsoft.
With increased tenant demand and rising rents, Dublin 18 is starting to see renewed speculative office development, with over 550,000 sq ft completed in 2017 including the new Microsoft HQ in South County. We expect greater interest from corporate occupiers to relocate to the suburbs this year, as rents, lease terms and availability better suit the profile to satisfy large space requirements. We predict prime rents in the suburbs will exceed €30.00 psf by the end of 2018 as supply tightens, with no significant increase in new construction until after 2019.
Outlook
With strong occupier demand and pipeline of enquiries, 2018 is shaping up to be another year of growth for the Dublin office market. New office completions for 2018 are predicted to be around 2.7m sq ft, with already close on 40% of this space reserved, so new stock is still not reaching a level to affect the current market imbalance for occupiers.
The continued shortage of Grade A space is one of the factors in the rise of the co-working sector in Dublin, with both WeWork and Iconic Offices in aggressive expansion mode in 2017. This market is serving the early phase technology companies who need maximum flexibility for growth, but also increasingly the corporate market for expansion and temporary project or ‘swing space’.
We are now less than 12 months from the introduction of new international accounting rules on 1 January 2019, which will bring all property leases onto corporate balance sheets to be recorded as a liability. This is likely to incentivise certain market sectors to seek more lease flexibility, and we have seen some examples of this in 2017 with companies opting for a shorter lease term initially with a right to extend, rather than the more traditional 20 or 25 year lease with tenant break option.
Headline office rents
| CBD (Grade A) | €65.00 per sq ft |
| Suburban (Grade A) | €30.00 per sq ft |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,500 pa per car space |
Market statistics, 2017
| Take up | 3.57m sq ft |
| Available space | 2.90m sq ft |
| Vacancy rate | 7.0% |
| New completions, 2017 | 1.97m sq ft |
| Pre-committed, Q4 2017 | 39% |
| Estimated completions, FY 2018 | 2.73m sq ft |
| Under construction, CBD | 3.5m sq ft |
| Under construction, suburbs | 0.48m sq ft |
Top 10 office deals, 2017
| Building | Size (sq ft) | Tenant |
|---|---|---|
| Microsoft HQ, South County, D18 | 370,000 | Microsoft |
| 100 & 300 Capital Docks, D2 | 216,000 | Indeed.com |
| The Beckett, East Wall Road, D3 | 170,000 | |
| Block H Central Park, D18 | 152,000 | AIB |
| Miesian Plaza, Baggot Street, D2 | 143,000 | OPW |
| 200 Capital Docks, D2 | 127,500 | JP Morgan |
| LinkedIn HQ, Lad Lane, D2 | 118,000 | |
| 10 Molesworth Street, D2 | 115,000 | AIB |
| The Atrium, Sandyford, D18 | 90,000 | Fleetmatics |
| One Ballsbridge, Shelbourne Road, D4 | 75,000 | Avalon |
29 January, 2018
2017 was a record year for the Dublin market with all the signs staying positive for the year ahead.
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.