26 August, 2017
HWBC releases its H1 Office Report and it receives widespread coverage
Our 2017 H1 Office Report which predicts prime office headline rents peaking at €65 psf next year has received widespread national and international coverage.

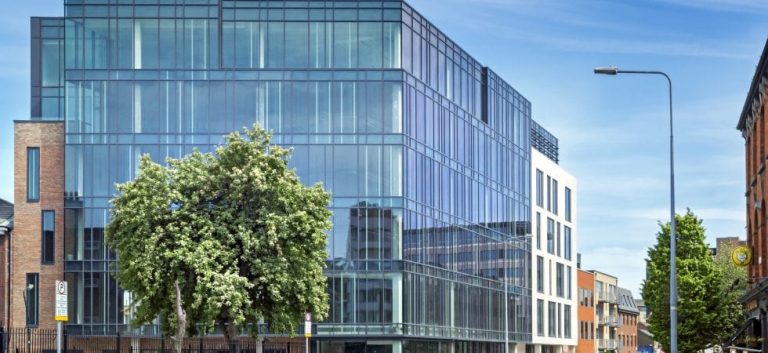
Another strong six months for the Dublin office market.
The Dublin office market had another strong six months, with take up of 1.67m sq ft recorded to the end of June, which is 55% ahead of the same period last year. The demand for space shows no sign of slowing, with over 2.0m sq ft of identified tenant requirements, which excludes the additional demand now starting to emerge from Brexit related tenants.
Notwithstanding the robust activity across all sectors, the market does appear to be entering a more mature phase in this cycle, with prime rents showing signs of levelling off and the vacancy rate likely to bottom out at around 7.0% for the entire market.
Supply and construction
The availability of modern space is still restricted in the CBD, with new completions not yet at a level to improve supply for corporate occupiers. Virtually all the visible cranes in the docklands are for office development, and the majority of new buildings are letting up during construction, with 89% of new completions this year pre-committed on or before practical completion. This high level of take up was the same in 2016, where over 90% of the buildings completed last year were pre-let, with typically most tenant activity in the final six months of construction.
There is a total of 3.89m sq ft under construction in Dublin, with around 3.15m sq ft of this city based and the balance mainly in the south suburbs of Sandyford and Leopardstown. There is also a large scheme on-site at Dublin Airport where up to 400,000 sq ft will be developed by the DAA.
With around 90% of new space being let on completion, there are no signs of the market being over-supplied in the medium term. Most of the space under construction will be completed by the end of 2018, and the level of new starts this year and next for completion beyond 2019 will be closely watched for signs of over-supply. The economy is still growing and approaching full employment levels, which is the principal driver of office demand in the financial, professional and services sectors.
Molesworth Street
The Molesworth Street area is seeing a huge regeneration, with three significant office buildings to be completed this year. 40 Molesworth Street (30,000 sq ft) has secured a single let to Jet.com, and One Molesworth Street has signed up Barclays for 35,000 sq ft. The old passport office at 10 Molesworth (115,000 sq ft), being developed by IPUT, is also rumoured to be reserved to a high profile financial tenant.
With the completion of the LUAS extension in 2017, this area has transformed into a new office quarter, along with the more traditional CBD locations of St Stephens Green, Earlsfort Terrace and Hatch Street.
Dublin, the post-Brexit location for global financial institutions
The South Docks has continued to see considerable activity in 2017, with Grant Thornton signing contracts for a new 125,000 sq ft HQ which is under construction at City Quay. Most of the crane activity is concentrated on the North and South Docks, with Capital Docks and Dublin Landings securing significant anchor tenants of JP Morgan and NTMA respectively.
The decision by JP Morgan to expand in Dublin is the first significant Brexit related move, with IDA Ireland predicting a flow of announcements later this year of high profile banks and insurance firms choosing Dublin as their post Brexit location. So far in 2017, fifteen global financial institutions such as Barclays, Citi, Bank of America and insurer Legal & General have announced their intentions to set up or expand their operations in Ireland.
The effects of Brexit on the Dublin market are still playing out, however companies do appear to be gearing up to make decisions on post Brexit moves over the next 12 months. Dublin’s main competition is Frankfurt, Paris and Amsterdam, and the low supply of suitable and affordable residential accommodation in Dublin will probably cost us investments over the short term.
Rents
The increase in prime headline rents is beginning to slow, with significant deals at €62.00 psf now being achieved for the top end of the CBD market. The highest rent achieved this year is a letting to a Chinese aviation company at €70.00 psf, for a smaller penthouse suite in One Ballsbridge on Shelbourne Road. Headline rents in the CBD are likely to top out at around €65.00 psf in this cycle over the next 12 months, as new supply provides more choice for occupiers.
Rents in the suburbs are a little earlier in their recovery phase and are expected to keep rising to around the mid €30s psf for the best buildings. This is a similar level to the peak in 2007 and provides a lower cost alternative for those companies not requiring a city presence.
Co-working and the suburbs
Along with other major cities such as London and New York, the rise of the co-working trend continues in Dublin, with Huckletree and the Iconic brand actively taking space in the market. The New York based WeWork are also looking at numerous sites in Dublin with a significant ongoing space requirement.
New speculative construction in the suburbs will take some pressure off the CBD and provide an alternative choice for tenants. So far schemes have mainly concentrated in Dublin 18 and Citywest, which are long established business hubs with extensive public transport, road and light rail infrastructure essential to attract the top occupiers.
Headline office rents
| CBD (Grade A) | €60.00 – €62.00 per sq ft |
| Suburban (Grade A) | €28.50 per sq ft |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,500 pa per car space |
Market statistics, H1 2017
| Take up | 1.67m sq ft |
| Available space (entire market) | 2.89m sq ft |
| Vacancy rate | 7.25% |
| Completions, 2017 | 0.93m sq ft |
| Pre-committed on practical completion | 87% |
| Under construction | 3.89m sq ft |
| Pre-committed | 31% |
| Estimated completions, FY 2017 | 2.54m sq ft |
| Estimated completions, FY 2018 | 2.28m sq ft |
2017 highlights
| 1.67m sq ft | Take-up recorded in the six months to the end of June |
| 15 | Global financial institutions to set up or expand their operations in Ireland in 2017 |
| 90% | Of new buildings in H1 pre-let on or before completion |
26 August, 2017
Our 2017 H1 Office Report which predicts prime office headline rents peaking at €65 psf next year has received widespread national and international coverage.
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.