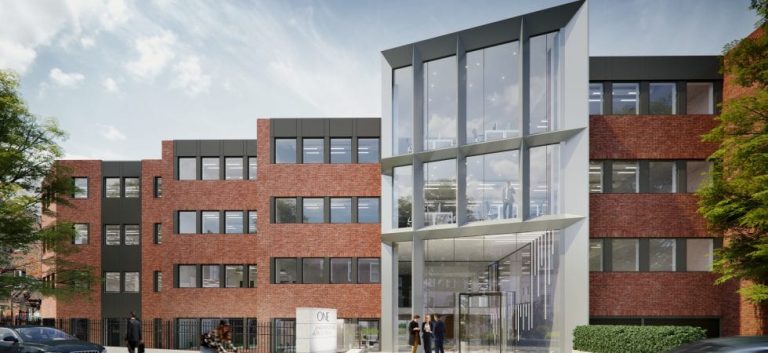
11 September, 2023
Press Coverage of HWBC Office Review & Outlook H1 2023
Catch up on all of the press coverage on our H1 2023 Office Report.

Dublin market continues in correction mode.
Office take up for the first six months at 678,000 sq ft is below the long-term half yearly average. The technology sector remains active on new take-up but not at previous scale. The average deal size has fallen to 7,500 sq ft, with 91 deals recorded in the first six months.
While the market has not stalled, the lower activity means occupiers remain cautious for the present on space requirements. The wider market has suffered adverse events over the last three years, and larger organisations continue to size their space needs for post Covid work practices. More companies will seek the return of employees to the office for a minimum three days a week, and in response more building owners will pursue multi-let strategies.
Key market statistics
Office supply and new construction
Suburbs
Outlook
The shift in how organisations use their office space results in reduced requirements relative to staff numbers with hybrid working. This shift forms part of the cocktail leading to lower transaction activity relative to the pre Covid market, and this trend will likely continue into the first half of next year. Despite a healthy level of reserved space of over 500,000 sq ft, take-up for the full year will struggle to reach 1.5m sq ft. The 2022 take up was higher at 2.32m sq ft and the 10 year average was 2.57m.
The shift to quality and energy efficient ‘green’ space has ensured prime rents have remained stable to date. There may be some pressure on headline rents and lease terms as new Grade A+ space enters the market for the limited number of larger active requirements. The rental and value gap to older generation space will continue to widen, making older buildings more difficult to let. Going forward these will be let on shorter lease terms as more flexible space. Buildings not suitable for upgrade to modern office needs will either be repurposed to alternative uses such as hotels, residential or student, and in some cases demolished.
With around 3m sq ft of new offices expected to be completed by the end of 2024, supply will increase and the vacancy rate rise. With few new construction starts expected from 2024, a lot of this space will be absorbed by current and new enquiries over the next two years as tenant demand is expected to recover from current levels.
WeWork’s financial difficulties have been well publicised. They currently lease four large office blocks and some floors in other buildings, with over 400,000 sq ft in Dublin’s CBD. While they may emerge from this current crisis, there is a possibility some of this space may return to the market as grey space or for reletting next year.
On a positive note, we think the market is well advanced through this correction which began in Q1 2022. Our expectation is market sentiment will turn in the first half of 2024 as capital values bottom out and the tap on new supply slows to a trickle. There was no new construction of office space for four years from 2011 to 2014, and this led to a build-up of demand and kickstarted recovery. We expect there to be a similar supply gap emerging, with few new speculative development starts in 2024 and 2025 leading to a potential shortage of the highest quality best in class space, which occupiers are increasingly focused on at the premium end of the market.
Headline office rents (H1 2023)
| CBD (Grade A) | €57.50 – €65.00 per sq ft (NIA) |
| Suburban (Grade A) | €30.00 – €34.00 per sq ft (GIA) |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,750 – €2,000 pa per car space |
Office statistics, H1 2023
| Take up, H1 2023 | 678,000 sq ft |
| Vacancy rate | 14.40% |
| New completions, H1 2023 | 390,000 sq ft |
| Pre-committed on completion | 28% |
| Under construction, CBD | 3.73m sq ft |
| Under construction, suburbs | 206,000 sq ft |
Top 5 office deals, H1 2023
| Building | Size (sq ft) | Tenant | Sector |
|---|---|---|---|
| Haymarket House, Smithfield, D7 | 79,600 | NTA | Government |
| Cadenza, Earlsfort Terrace, D2 | 39,200 | KKR | Finance |
| Termini, Sandyford, D18 | 30,500 | Jacobs | Professional services |
| Harcourt Square, Harcourt Street, D2 | 27,100 | KPMG | Professional services |
| 2 Stemple Exchange, Blanchardstown, D15 | 22,900 | Synopsys | Technology |
11 September, 2023
Catch up on all of the press coverage on our H1 2023 Office Report.
6 September, 2023
Dublin market continues in correction mode. Read our full Office Report here.
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.