4 September, 2024
Press Coverage of HWBC Office Review & Outlook H1 2024
Catch up on all of the press coverage on our H1 2024 Office Report.

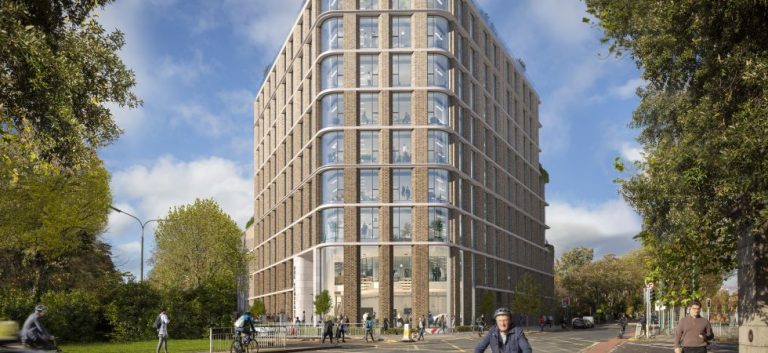
Strong rebound in Q2 lettings as market on track to exceed 2m sq ft full year take up.
The recovery in office demand in Dublin has been gathering pace and saw a sharp rebound in Q2, with 900k sq ft of signed deals to bring the total for the first half of the year to 1.1m sq ft. The strong performance in Q2 had been building over the previous quarters, with weak take up in Q1 arguably marking the low point of the cycle. There was only one deal over 50k sq ft in the entire of 2023, and this year has already had five with more to come in the second half of the year.
Key market statistics
Office supply and new construction
Suburbs
Outlook 2024
There is growing consensus that this year will mark the low point of the cycle, with a number of positive indicators including increased demand from corporate occupiers and steady absorption of the overhanging grey space on the market. The new supply of speculative office space will see a dramatic fall next year, which will start to put pressure on the top tier of the CBD market where most of the demand is focused. Interest rates are on a downward trajectory, which should provide some certainty for business on costs looking at investment and expansion.
The top tier of the market is performing well, but the outlook for older office buildings with poor BER ratings is not so positive. Terms on these buildings will continue to soften as landlords offer ever more attractive terms to secure lettings for empty floors. For occupiers, the next six months may mark the ‘sweet spot’ to acquire space on the most favourable terms as the market slowly corrects in terms of quality supply available.
With the pandemic firmly in the rear-view mirror, companies are increasingly making decisions on office requirements for the medium term, with big names like EY, Deloitte, BNY, Citi and Workday all showing confidence in the importance of the physical office for staff, clients and future growth. More certainty on occupier strategy is leading to increased activity on the investment side, with significant volumes of capital looking to invest in the Dublin office market for the right product at the right price. We expect investors to start reviewing suitable CBD sites for the next construction cycle, to deliver into an under supplied post 2026 market.
Headline office rents (June 2024)
| CBD (Grade A) | €57.50 – €62.50 per sq ft |
| Suburban (Grade A) | €28.00 – €34.00 per sq ft |
| Car spaces, city | €4,000 pa per car space |
| Car spaces, suburbs | €1,750 – €2,000 pa per car space |
Office statistics, H1 2024
| Take up, H1 2024 | 1.1m sq ft |
| Vacancy rate (entire market) | 16.5% |
| New completions, H1 2024 | 1.4m sq ft |
| Pre-committed on completion | 35% |
| Under construction, CBD | 2.725m sq ft (52% reserved) |
| Under construction, suburbs | n/a |
Top 5 office deals, H1 2024
| Building | Size (sq ft) | Tenant | Sector |
|---|---|---|---|
| The Seamark Building, D4 | 182,000 | HSE | Government / health |
| One Wilton Park, D2 | 156,000 | Stripe | Technology |
| The Shipping Office, D2 | 79,000 | BNY Mellon | Finance |
| Building G3 Cherrywood, Co. Dublin | 60,000 | APC | Health |
| 3-8 Hume Street, D2 | 49,000 | Iconic Offices | Professional |
4 September, 2024
Catch up on all of the press coverage on our H1 2024 Office Report.
4 September, 2024
Strong rebound in Q2 lettings as market on track to exceed 2M sq ft FY take up.
Email PaulEmail: pscannell@hwbc.ie
08722604730872260473
In line with Government advice and for the benefit of everyone, HWBC's Harcourt Street offices are closed until further notice. We remain fully operational remotely and you should continue to contact us in the normal way. Contact details for all staff can be found by clicking on the link below, stay safe.
Find out moreAfter graduating with a Diploma in Property Economics (DIT, Bolton Street), BSc (Surv) (Trinity College Dublin) and a Diploma in Business Studies (Smurfit Graduate School of Business, UCD) Paul began his career in the Office Agency department of Hamilton Osborne King in 1995 before moving to Palmer McCormack in 1997 where he was made Partner in 2001 and then joined HWBC on its foundation in 2005 as a Director.
Paul has extensive experience acting on behalf of Landlords, Tenants, Developers and Institutions giving a broad perspective on the occupational, letting, sales and development for the Dublin Office Market.
Recent major transaction include:
The underwrite and pre-funding of the Vertium Building (172,000 sq ft) for Union Investment in 2015.
Acquisition and re-letting advice on Pelham House, South County for Friends First in 2015-2016.
Acquisition, development and letting of The HIVE Sandyford (73,000 sq ft) on behalf of U+I Group plc
Roles & Responsibilities within HWBC
Paul is a qualified Chartered Surveyor and Director in charge of Office Agency in HWBC.